
Section 148A of Income Tax Act
Complete Guide to Reassessment, Time Limits, Rights, Procedure, and How to Reply
DISCUSS WITH EXPERT
Why is notice issued under Section 148A?
The income tax officer can issue notice u/s 148A if they have information that you have hidden some income or asset in the return filed by you.
The Income tax department gets information from all Financial Institution, Bankers, Registrar , Fund Broker etc. wherever your PAN is linked. If the information got by the Income Tax dept does not match with your Income Tax return, then the officer can issue notice u/s 148A.
There are some common reason of issue of Income tax Notice when Income tax return does not match with information:
- Cash Deposit more than 10 Lac
- Cash withdrawal of more than 10 Lac
- Property Purchase above value Rs.25 lac
- Property Sold but not reported
- FDR above Rs.15 Lac
- Credit Card Bill Payment above Rs.5 lac
- High Agriculture Income reported
- TCS/TDS deducted but income not offered
- Sale reported in GST mismatch with Income Tax Return
- Purchase of High value Vehicle than income
- Investments of high value in Shares/Mutual Fund than Income
- Third party document/information received by Officer related to you.
For Example:
- A has sold some shares of XYZ company but he did not report in his ITR, then he may get notice u/s 148A.
- B has deposited cash in the Bank amount to Rs.10 lac, but his return does not have any information related to cash deposit source, he may get notice.
- C has paid credit card bills amounting to Rs.4 lac and his annual income reported in ITR does not signify such usage of card payment, he may get notice.
- D purchased property worth Rs. 50 lac then also income tax officer issued notice to get more details of sources of funds to buy property.
- E has some foreign bank account but he did not report these bank details in ITR.
Ready to try Easy Return?
Download on Google Play and start checking Your TDS instantly.
What Exactly Is Section 148A?
Section 148A is the legal notice that stands between the tax department and your completed tax return.
It ensures that before your tax case is opened:
- You are informed
- You are heard
- You are given evidence
- The officer must apply his mind
- A written order must be passed
This makes assessment fair, transparent, and legally sound.
Section 148 vs 148A vs 147 – Explained Simply
Section | Meaning |
147 | Allows reassessment if income escaped |
148 | Legal notice to reopen assessment |
148A | Mandatory process before 148 |
148A is the gatekeeper.
Without passing through it, no reassessment is valid.
4. Who Can Issue Section 148A Notice?
Only an Assessing Officer having jurisdiction over your PAN can issue a Section 148A notice. The officer must obtain approval from:
- Joint Commissioner / Additional Commissioner
- Principal Commissioner / Commissioner
This ensures no junior officer misuses the power.
Ready to try Easy Return?
Download on Google Play and start checking Your TDS instantly.
5. Detailed Step-By-Step Procedure Under Section 148A
Step 1 – Information Reaches AO
AO gets data (e.g., ₹40 lakh bank deposit).
Step 2 – AO Evaluates
AO must check if this income is already disclosed.
Step 3 – Inquiry (If Needed)
AO may:
- Get bank statement
- Verify ITR
- Call for GST records
- Seek approval
Step 4 – Show Cause Notice
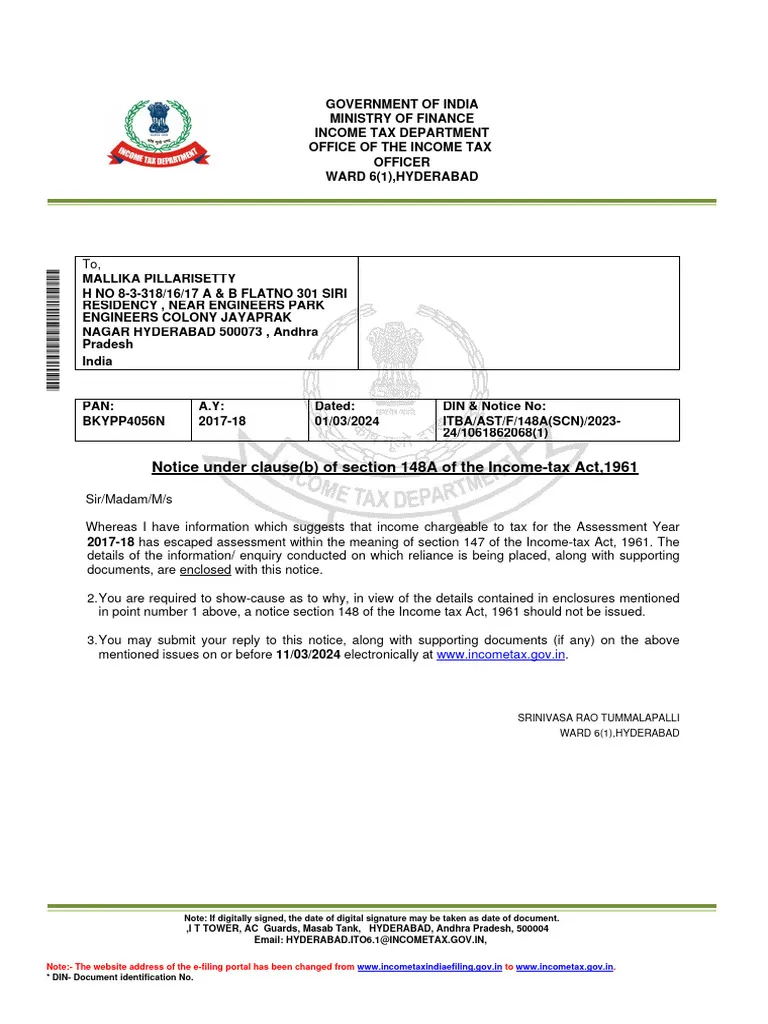
You receive a 148A(b) notice explaining:
- What is the issue
- What amount
- Which year
Step 5 – Your Reply
You submit:
- Explanation
- Documents
- Proof of source
Step 6 – AO’s Speaking Order
AO passes 148A(d) order deciding:
- Whether reopening is justified
Step 7 – 148 Notice (if approved)
Only after this, reassessment starts.
Ready to try Easy Return?
Download on Google Play and start checking Your TDS instantly.
6. Time Limits After Finance Act 2024
Income Escaped | Max Reopening |
< ₹50 lakh | 3 years |
≥ ₹50 lakh | 5 years |
This is a major reform. Earlier it was 10 years.
7. How to reply to notice u/s 148A?
The notice shall have complete details and reason for issuance of Notice.
Let’s Say, Mr. Mehra got notice because he has purchased a flat of Rs.1.25 crore and his annual income from salary is Rs.20 lac.
The notice shall ask the following detail and documents-
- Seller of Property
- Register Deed/Allotment Document
- Complete address of Flat
- Payment details of Property
- Source of your Funds to buy property
In this case, you have to reply to each & every point to convince the officer that all transactions made by you are genuine.
The reply shall be made point wise of notice issued-
- Name, Address, PAN of Property Seller
- The Allotment letter of Flat
- Payment Details– You have to attach the Bank statement from where the payment has been made. Each payment entry made from all banks shall be highlighted to the officer. If there is over payment or lesser payment found from the bank , the AO can penalize under or over payment than shown in the allotment letter.
- Source of Fund: You need to show the sources of funds deposited by you in the bank to buy property. These sources could be your old bank balance lying in account, Old FDR, Sale proceeds from Share, Properties etc., Fund received from family like Parents , Siblings etc, Loan taken from Banks.
If you have deposited immediate cash in a bank to buy property you need to give proof of the source of cash. It is almost hard to prove a cash deposit above Rs.5 lac unless you have high income or shown cash withdrawal from the bank in recent months.
You cannot say you have borrowed cash from friends or someone to deposit money in a bank , because a cash loan from anyone above Rs.20000/- is not allowed in India u/s 269S.
After receiving the reply to notice, the Income tax check if reply is adequate then they may drop the notice proceeding. If the reply is inadequate they may issue further notice and ask more information till they find the transaction is genuine or ingenuine.
It is taxpayer duty to prove themselves that the transactions made by them are genuine. In case the Taxpayer is unable to prove the transactions, the officer may issue Tax and notice demand.
8. What are the penalties of non replying to notice 148A?
The notice does not have an amount wise penalty. However, it can cause much higher harassment on non replying to it. This shall give the Tax officer more power to ask much more details & documents which may not be required at initial level reply. Because the officer can issue notice u/s 142(1) and 144, or 147 on replying to notice.
It is always advised to reply adequately to notice u/s 148A to ignore further notice and litigation.
9. Who can reply to notice 148A?
The reply to income tax notice can be given self or by CA also. This process of notice involves technical sections and detailed study of cases and transactions.
It is always advised to consult CA in income tax notice.
10. How to reply to Notice 148A?
The reply to notice is made online through the Income Tax portal.
Step 1: Login to Income Tax Portal
Step 2: Check for E-Proceeding & Assessment tab
Step 3: Click on submit reply to notice
Step 4: Now select the type of documents like Bank statements, Property Documents etc.
Step 5: Attach & Submit the documents in PDF file only.
If you have not prepared all documents you may submit partial reply or seek adjournment of date for gathering details by giving reason.
When Section 148A Is Not Required
148A is not needed when:
- Search u/s 132
- Requisition u/s 132A
- Black Money Act cases
- Benami Property cases
Because such cases already have strong evidence.
Ready to try Easy Return?
Download on Google Play and start checking Your TDS instantly.
11. Rights of Taxpayers Under Section 148A
You have:
- Right to see evidence
- Right to reply
- Right to request extension
- Right to hearing
- Right to appeal
- Right to challenge illegal reopening
12. Common Triggers for Notices
- Large cash deposits
- Property deals
- Crypto trading
- Share trading
- GST mismatch
- Foreign income
- TDS mismatch
- High credit card spending
11. What Happens If You Ignore 148A Notice
Ignoring leads to:
- Reassessment
- Tax + penalty
- Interest
- Prosecution risk
12. How to Draft a Strong Reply
A good reply should include:
- Legal denial
- Factual explanation
- Documentary proof
- Accounting records
- Bank statements
- ITR reconciliation
13. Real-Life Examples
Bank Deposit
AO alleges ₹30 lakh deposit.
You show loan + withdrawals.
Notice dropped.
Property Purchase
AO sees ₹2 crore deal.
You show loan + old property sold or fund sources.
Case closed.
14. Why Courts Support 148A
Courts have ruled:
“No reassessment without opportunity is unconstitutional.”
15. Final Conclusion
Section 148A has transformed Indian tax law from a power-centric to a justice-centric system. It gives taxpayers:
- Voice
- Protection
- Evidence
- Due process
Understanding this section is the best defense against wrongful tax reopening.
Ready to try Easy Return?
Download on Google Play and start checking Your TDS instantly.
Frequently Asked Questions (FAQs) on Section 148A of Income Tax Act
Section 148A is a legal provision that requires the Income Tax Department to give a taxpayer an opportunity to explain their case before reopening an old income tax return. Earlier, the tax department could reopen assessments directly by issuing a notice under Section 148. Now, under Section 148A, they must first send a show-cause notice, consider the taxpayer’s reply, and then decide whether reopening is justified. This protects taxpayers from arbitrary or unfair reassessment.
Section 148A was introduced to stop the misuse of reassessment powers by tax officers. In the past, many notices were issued without giving taxpayers a chance to explain. This led to harassment and court cases. The government added Section 148A to ensure fairness, transparency, and natural justice by allowing taxpayers to be heard before any reassessment begins.
Section 148 allows the Income Tax Department to issue a notice for reopening a tax return. Section 148A, on the other hand, lays down the mandatory procedure that must be followed before issuing that notice. In simple words, Section 148A comes first and gives you a chance to reply, while Section 148 is issued only after the officer decides to reopen the case.
A Section 148A notice means the Income Tax Department has received some information suggesting that your income might have been under-reported or not taxed properly. It does not mean that you are guilty. It only means that the department wants to hear your explanation before deciding whether to reopen your tax return.
You are given a minimum of 7 days and a maximum of 30 days to submit your reply. If you need more time, you can request an extension from the Assessing Officer. It is very important to reply within the given time to avoid further action.
After receiving your reply, the Assessing Officer will review your explanation and documents. Then, the officer will pass a written order called a “speaking order” under Section 148A(d). Based on this order, the officer will decide whether to issue a reassessment notice under Section 148 or drop the matter.
No, in normal cases they cannot. Section 148A makes it mandatory for the department to give you an opportunity to be heard before reopening your assessment. Only in special cases like search and seizure operations can the department skip this step.
A Section 148A(d) order is the written decision of the Assessing Officer after considering your reply. It explains whether the department believes your income escaped assessment and whether a reassessment notice under Section 148 should be issued.
As per the latest law, if the escaped income is less than ₹50 lakh, the department can reopen your case up to 3 years from the end of the relevant assessment year. If the escaped income is ₹50 lakh or more, the case can be reopened up to 5 years.
Section 148A does not apply in cases where there is a search under Section 132, seizure under Section 132A, or cases under special laws like the Black Money Act or Benami Property Act. In such cases, the department can directly issue a reassessment notice.
Under Section 148A, you have the right to know the reasons for reopening, see the evidence relied upon, submit your explanation, request extra time, and challenge any unfair or illegal reassessment.
If you do not reply, the Assessing Officer may assume that you have no explanation and proceed to issue a reassessment notice under Section 148. This can lead to additional tax, penalties, and interest.
Yes. If you believe the order is incorrect or violates the law, you can challenge it before higher tax authorities or courts.
Notices are commonly issued for large cash deposits, property purchases, share trading profits, foreign income, GST mismatches, or bank transactions that do not match the income shown in the tax return.
Yes. Section 148A is a major protection for taxpayers because it ensures that the tax department cannot reopen your tax return without first listening to you and examining your explanation.